
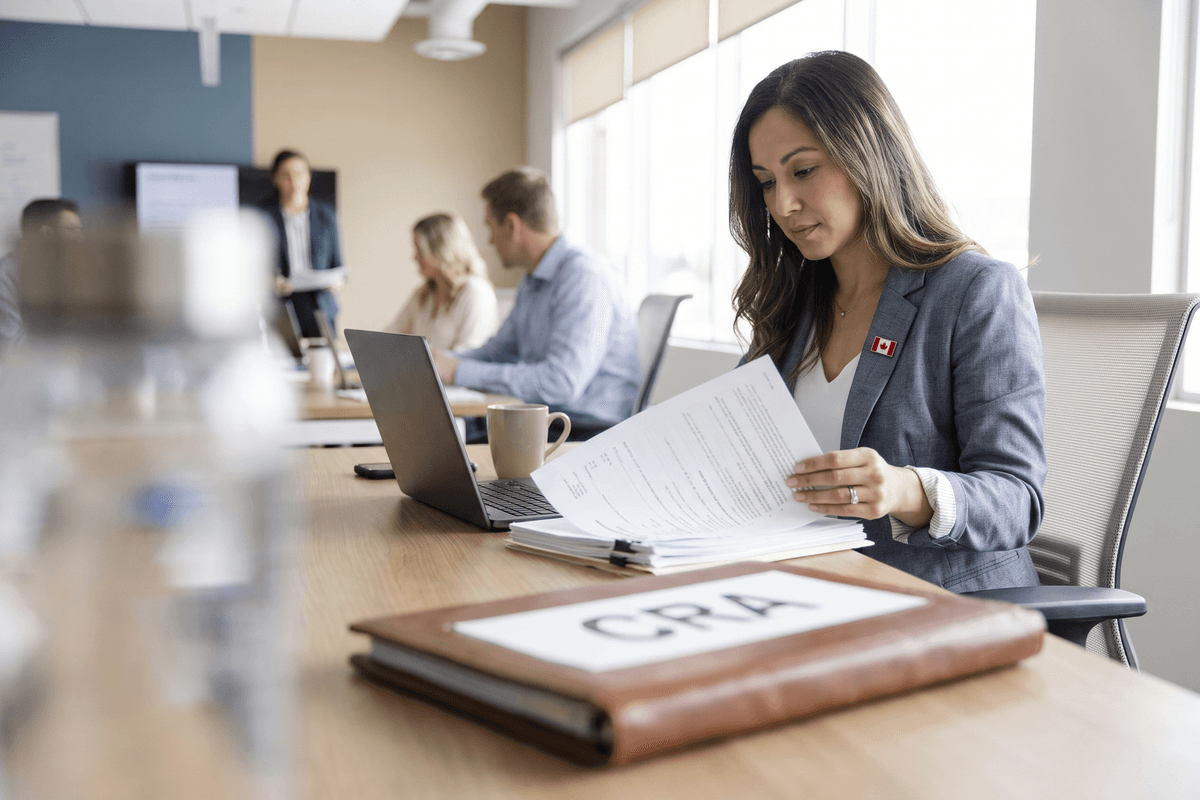

A single letter from the Canada Revenue Agency (CRA) can land on an accounting firm's desk with a deadline measured in weeks, not months. For a practice that holds years of client files, that letter can trigger a legal obligation, a solicitor-client privilege dispute, and a reputational risk all at once. The first thirty days after receipt often determine whether a firm protects its clients and itself or finds itself negotiating from a weak position.
Why a Requirement Lands on Your Desk
The CRA can compel third parties to produce information when it is auditing or examining a taxpayer's affairs. Accounting firms are frequent recipients because they hold the working papers, correspondence, and ledgers that the agency wants to review. A requirement may target a single client or a broader group of files, and it may be framed around a specific tax issue, a promoter, or a planning arrangement.
The legal authority behind these demands is significant, and non-compliance carries real consequences. Firms that treat a requirement as routine correspondence risk missing a deadline that cannot be reopened easily. The primary source frames this first month as the critical window for procedural decisions.
The First Thirty Days: A Step-by-Step Playbook
The most effective responses follow a disciplined sequence. Rushing to hand over files before reviewing them is one of the most common and costly mistakes.
Days 1 to 3: Verify and Log
- Confirm authenticity and scope. Check the requirement's legal basis, the named taxpayer, the date, and the exact categories of records requested.
- Log the receipt date. The clock typically starts on receipt, so record when and how the document arrived.
- Notify the firm's legal counsel. Early involvement protects privileged material and helps set the response strategy.
- Issue a preservation notice. Staff must not alter, delete, or destroy any potentially responsive records.
Days 4 to 10: Scope and Privilege Review
Once the scope is clear, the team should identify which documents fall within it. This is also the stage to flag material that may be protected by solicitor-client privilege or litigation privilege. Privileged documents must be separated and logged rather than quietly included in the production set.
Days 11 to 30: Respond, Document, and Negotiate
By the third week, the firm should decide on its position. Common paths include full compliance, partial compliance with written objections, a request for an extension, or a legal challenge. Each has trade-offs.
| Response Option | When It Fits | Main Risk |
|---|---|---|
| Full compliance | Records are clearly within scope and non-privileged | Waiving privilege or over-disclosing unrelated client data |
| Partial compliance with objections | Some records are privileged or overbroad | The CRA may escalate or seek a court order |
| Extension request | Volume or complexity makes the deadline unrealistic | Denial, leaving the firm with less time than expected |
| Judicial challenge | The requirement is unreasonable or privilege is at stake | Cost, time, and public scrutiny |
Whatever path is chosen, every decision should be documented in writing. A clear paper trail of what was produced, withheld, and why is essential if the matter reaches court.
Lessons from the KPMG Canada Litigation
Recent federal court proceedings involving KPMG Canada have sharpened the profession's understanding of how far CRA demands can reach and where the limits lie. The analysis of this litigation highlights procedural obligations and privilege issues that every firm should understand before a requirement arrives.

The central lesson is that a firm's own records are not automatically exposed to CRA review, but claims of privilege must be asserted carefully, specifically, and with evidence.
The practical implication is that privilege is not a blanket shield. A firm that wants to protect communications must be able to show what is privileged, why, and how the claim was tested against the requirement. Generic objections are unlikely to succeed.
Practical Implications for Firms
- Build a privilege protocol now. Define how engagement letters, legal advice, and working papers are marked and stored.
- Train staff on escalation. Front-desk and administrative staff should know to forward any CRA correspondence immediately.
- Maintain a privilege log. Itemized logs make disputes easier to resolve and strengthen the firm's credibility.
- Review engagement terms. Clients should understand how the firm will respond to government demands.
Emerging Penalty Risk: The Daily Non-Compliance Debate
Beyond individual requirements, the profession is watching proposed changes to CRA audit compliance powers. CPA Canada leadership has warned lawmakers about unintended consequences, particularly automated daily penalties, which have been described as potentially reaching innocent taxpayers and small businesses without warning.

For accountants, the concern is twofold. First, a firm may be the party that must gather information quickly, and a daily penalty clock makes delays more expensive. Second, clients may be penalized for administrative gaps that they did not understand or control. Firms that advise small business clients should be prepared to explain these risks and to help them organize records before any audit begins.
The Business Context: Growth Meets Policy Change
The stakes of this work are rising alongside the profession itself. Statistics Canada reports that accounting, tax preparation, bookkeeping, and payroll services generated $31.9 billion in operating revenue, with steady top-line growth across provincial markets. A profession of that scale handles an enormous volume of sensitive client data, which makes information requests a recurring operational reality rather than a rare event.
Policy is changing too. The newly tabled federal budget includes a flagship Productivity Mega Deduction and accelerated capital deduction rules that will reshape tax planning for corporate clients. Accountants advising on these incentives should also think about documentation. Claims made under accelerated rules are the kind of positions that may attract CRA review, so the supporting files need to be organized from the start.

Looking Ahead: Preparing Before the Letter Arrives
The most important shift for Canadian accounting firms is to treat CRA readiness as an ongoing practice rather than a crisis response. That means maintaining clean records, defining privilege protocols, training staff, and rehearsing the thirty-day process before it is needed. Firms that do this will be able to respond with confidence, protect client confidentiality, and challenge overreach where necessary.
As litigation clarifies the boundaries of CRA powers and policymakers debate new penalty structures, the firms that adapt earliest will be best positioned. The next requirement letter may already be in the mail. The question is whether the firm's first thirty days are planned or improvised.