
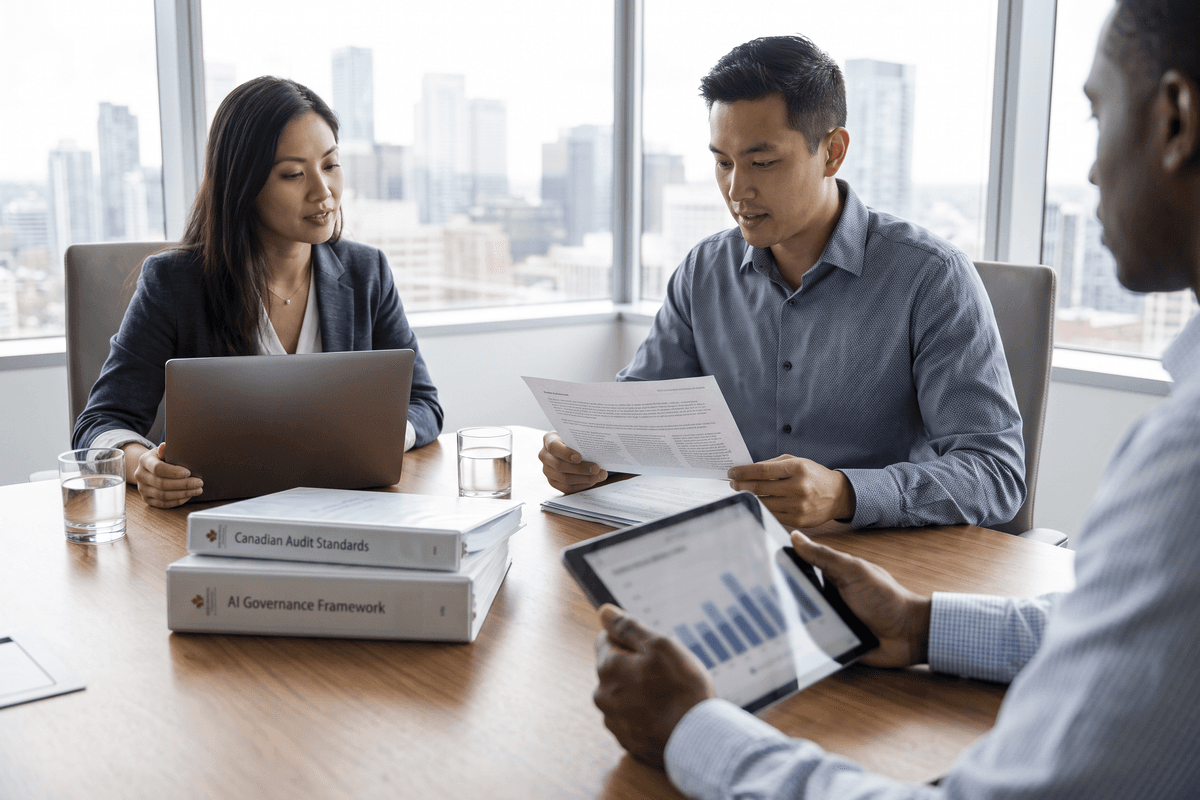


The accounting profession is navigating a dual transformation: the rapid integration of artificial intelligence into day-to-day assurance workflows alongside increasingly rigorous regulatory enforcement. As highlighted in recent industry roundups from Going Concern's Friday Footnotes, AI has surged to the forefront as the leading ethical dilemma facing modern accountants, even as regulators such as the Canadian Public Accountability Board (CPAB) intensify scrutiny over audit quality and firm compliance. For Canadian practitioners, this shifting landscape demands a proactive reassessment of professional skepticism, data governance, and regulatory accountability.

The AI Dilemma: Ethical Risk at the Top of the Agenda
According to findings highlighted by global accounting bodies including the Association of Chartered Certified Accountants (ACCA), artificial intelligence has officially surpassed traditional compliance concerns as the primary ethical challenge facing finance professionals. While automated workpapers, anomaly-detection algorithms, and generative AI reporting tools offer unprecedented efficiencies, they also present complex risks that directly challenge core tenets of professional integrity and objectivity.
"The rapid rise of AI across financial workflows has fundamentally shifted the ethical calculus for practitioners. Automated output can never replace the professional skepticism and human judgment required of a licensed CPA."
Core Ethical Risks Confronting Practitioners
- Algorithmic Bias and Hallucinations: Relying on unverified machine learning models for risk assessment or transaction sampling can lead to blind spots and misstated risk profiles.
- Client Confidentiality and Data Sovereignty: Uploading sensitive corporate data or non-public financial records into public or multi-tenant cloud-based AI tools breaches fundamental confidentiality standards under provincial CPA Codes of Professional Conduct.
- Over-Reliance and Erosion of Skepticism: Automation bias poses a real threat when junior auditors accept AI-generated reconciliations without corroborating underlying source evidence.
- Explainability and Audit Trails: If an auditor cannot clearly explain how a model derived its conclusions, those conclusions cannot withstand regulatory inspection.
Implementing AI Practice Aids in Audit Engagements
Recognizing both the power and the vulnerabilities of artificial intelligence, professional standards bodies are rolling out targeted practice aids to guide audit teams through technology-driven engagements. In Canada, where firms must strictly adhere to the Canadian Auditing Standards (CAS), integrating AI tools into audit methodology requires clear safeguards.

To safely operationalize AI practice aids, Canadian audit firms should follow a structured three-pillar framework:
- Tool Validation and Vendor Due Diligence: Audit committees and firm quality leaders must evaluate third-party tools to verify training data integrity, encryption standards, and compliance with Canadian privacy legislation (PIPEDA).
- Standardized Documentation of AI Workpapers: Working papers must explicitly document model parameters, prompt engineering strategies, and specific human verification steps undertaken to validate the algorithm's findings.
- Mandatory Staff Training on Prompting and Verification: Junior and senior staff require training not just on how to execute AI prompts, but on how to critically challenge the generated outputs.
Canadian Audit Watchdogs Tighten Enforcement
While technology evolves, traditional audit quality and regulatory accountability remain under a bright spotlight in Canada. The Canadian Public Accountability Board (CPAB), the national regulator overseeing public company audit firms, has progressively signaled an era of increased transparency and decisive enforcement actions.
Recent enforcement settlements and supervisory updates published by CPAB highlight recurring inspection findings around engagement quality control reviews, revenue recognition verification, and adequate documentation of complex accounting estimates. Regulators are increasingly intolerant of superficial compliance, stressing that firm growth and technological adaptation must never compromise quality management systems (CSQM 1 and CSQM 2).
Ethical & Regulatory Matrix: Risks vs. Practical Mitigations
| Challenge Area | Regulatory / Ethical Risk | Recommended Mitigation for Canadian CPAs |
|---|---|---|
| Client Data & GenAI | Data leaks, PIPEDA violations, breach of client confidentiality. | Deploy enterprise private-instance LLMs; prohibit public cloud tools for client files. |
| Audit Evidence Quality | CPAB deficiency findings due to insufficient independent verification. | Treat AI outputs as initial leads; corroborate with direct third-party and source documentation. |
| Professional Judgment | Automation bias leading to missed material misstatements. | Incorporate mandatory manual review checkpoints in engagement quality reviews (EQR). |
Strategic Priorities for Canadian Accounting Leadership
To effectively manage the intersection of emergent AI tools and heightened regulatory oversight, Canadian accounting firms and finance teams must embrace proactive governance.
1. Establish an AI Ethics and Governance Committee
Mid-tier and national firms should establish multidisciplinary committees that include assurance partners, IT specialists, and legal counsel. This team should review and approve every automated tool before it is deployed on client engagements.
2. Revisit Engagement Quality Control Mechanisms
With CPAB increasing focus on firm governance, firms must ensure their quality control reviews thoroughly examine how technology was applied during high-risk audit areas, particularly estimates, fair value calculations, and journal entry testing.
3. Cultivate Tech Literacy Grounded in Ethical Foundations
Professional development must move beyond technical software training. Continuous professional development (CPD) programs must instruct staff on identifying synthetic data, recognizing algorithmic biases, and upholding their duty of care under professional standards.
Conclusion: Balancing Innovation with Public Trust
The transition toward AI-powered finance is inevitable, offering immense potential to eliminate repetitive tasks and deepen analytical insight. However, as ongoing audit enforcement actions and global ethical surveys indicate, technology does not reduce professional responsibility—it amplifies it. For Canadian CPAs, the path forward requires embracing innovation while anchoring every practice in rigorous skepticism, transparency, and uncompromised public trust.