
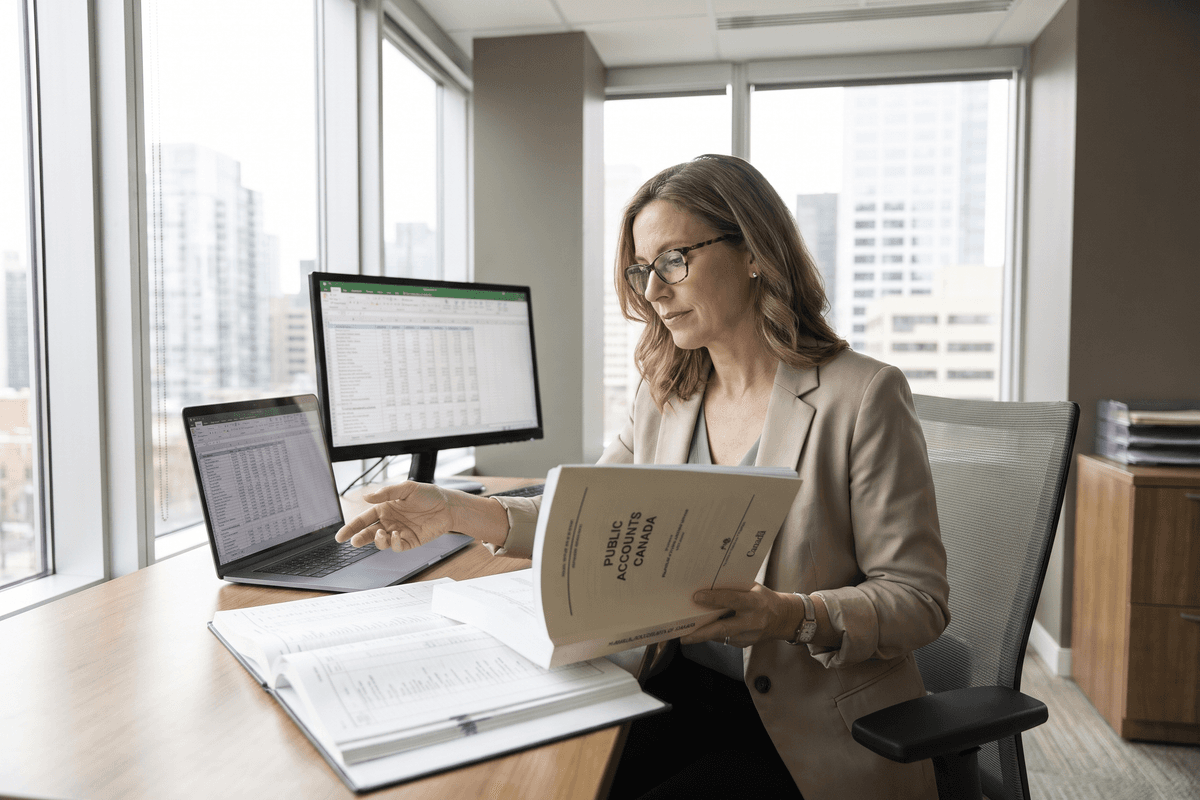
When the Receiver General of Canada tables the annual consolidated financial statements of the federal government, Canadian financial leaders are handed the most comprehensive balance sheet in the nation. The release of the Public Accounts of Canada 2026 provides far more than a routine retrospective on budgetary revenues and departmental expenditures; it represents the ultimate stress test of Canadian Public Sector Accounting Standards (PSAS). Marking another consecutive unqualified—or "clean"—audit opinion issued by the Auditor General of Canada, the 2025–26 fiscal report serves as a benchmark for audit readiness, sovereign risk management, and the robust application of complex accrual accounting frameworks.

The Sovereign Ledger: Anatomy of the 2025–26 Financial Results
The Public Accounts comprise three foundational volumes: Volume I details the audited consolidated financial statements of the Government of Canada; Volume II outlines departmental expenditures by program and standard object; and Volume III provides supplementary information, including federal transfers, court awards, and minister office expenses. For professional accountants, Volume I is the definitive document for scrutinizing sovereign fiscal health and accounting policy execution.
During the 2025–26 fiscal cycle, federal fiscal results navigated structural shifts in global bond yields, normalized post-pandemic program interventions, and fluctuating resource royalties. Total budgetary revenues reflected steady baseline corporate and personal income tax receipts, even as higher borrowing costs influenced public debt charges.
"An unmodified audit opinion from the Auditor General of Canada on sovereign financial statements is not merely a procedural victory; it is an international signal of institutional stability, transparency, and technical precision in financial reporting."
The consistency of the audit opinion is particularly notable given the scale of consolidation. The government entity encompasses over 100 departments, agencies, consolidated Crown corporations, and enterprise Crown corporations (such as Canada Mortgage and Housing Corporation and Export Development Canada), all harmonized through standardized reporting packages and consolidation adjustments.
Comparative Fiscal Performance Overview
To contextualize the accounting figures released by the Receiver General, the table below highlights the comparative trajectory of core balance sheet and statement of operations line items over recent reporting periods:
| Fiscal Metric (CAD Billions) | 2023–24 (Actual) | 2024–25 (Actual) | 2025–26 (Public Accounts) | Accounting Basis / Notes |
|---|---|---|---|---|
| Budgetary Revenues | $461.3 | $478.5 | $498.2 | Full accrual; tax accruals net of doubtful accounts |
| Program Expenses | $448.2 | $462.1 | $479.4 | Excludes public debt charges; includes federal transfers |
| Public Debt Charges | $47.5 | $51.2 | $54.6 | Reflects interest rate pass-through on market debt |
| Annual Deficit | $34.4 | $34.8 | $35.8 | Operating shortfall under full accrual accounting |
| Federal Debt (Accumulated Deficit) | $1,232.0 | $1,266.8 | $1,302.6 | Cumulative balance of annual operating results |
| Federal Debt-to-GDP Ratio | 41.8% | 41.5% | 41.1% | Economic sovereign solvency indicator |

Critical Accounting Standards in Focus
Achieving an unqualified audit opinion across an enterprise the size of Canada's federal administration requires resolving highly complex standard-setting challenges. In the 2025–26 report, several critical accounting standards took center stage:
1. Asset Retirement Obligations (PS 3280)
The full implementation of PS 3280 (Asset Retirement Obligations) continues to shape sovereign capital reporting. The federal government possesses one of the most geographically diverse portfolios of physical capital in the world, spanning defence bases, navigational infrastructure, radio towers, scientific research laboratories, and contaminated northern mine sites. Under PS 3280, the Receiver General must ensure that:
- Legal obligations associated with the retirement of tangible capital assets are recognized at fair and estimated settlement values upon asset acquisition or contamination event.
- Accretion expense is systematically calculated and recognized annually, reflecting the time value of money on remediation liabilities.
- Capitalized remediation costs are amortized over the remaining useful life of the underlying assets.
2. Financial Instruments Suite (PS 3450, PS 2601, and PS 1202)
The standard on Financial Instruments (PS 3450), paired with Foreign Currency Translation (PS 2601) and Financial Statement Presentation (PS 1202), introduced the Statement of Remeasurement Gains and Losses to public sector accounting. The government’s extensive use of interest rate swaps, cross-currency basis swaps, and forward contracts within the Exchange Fund Account requires precise fair value classification and disclosure of hedge relationships to mitigate artificial volatility in the Statement of Operations.
3. Public Sector Pensions and Employee Future Benefits
Pensions and other future employee benefits represent one of the federal government’s largest non-debt liabilities. Key auditing friction points regularly center around:
- Actuarial Discount Rates: The discount rates utilized to calculate the present value of accrued benefit obligations must reflect long-term borrowing costs and yield curves under PS 3250.
- Market Volatility: Smoothing of actuarial gains and losses over the expected average remaining service life (EARSL) of participating public sector employees.
- Inflation and Wage Indexation: Updating demographic and inflation expectations in line with collective bargaining agreements concluded across the core public service.
4. Contingent Liabilities and Specific Claims Settlements
Evaluating provisions under PS 3300 (Contingent Liabilities) remains one of the most judgment-intensive areas of the federal audit. The government continues to resolve historical legal disputes, including comprehensive land claims, specific claims, and childhood well-being settlements with Indigenous peoples. The accounting team must classify exposures into three strict categories:
- Accrued Liabilities: Where future settlement outflows are deemed likely and reasonably estimable.
- Note Disclosures: Where the likelihood is indeterminable, or where an outflow is likely but an amount cannot be reasonably quantified.
- Undisclosed Contingencies: Claims considered frivolous or unlikely to succeed.
Practical Implications for Canadian CPAs and Financial Controllers
The methodology and disclosures featured in the Public Accounts of Canada 2026 provide direct, actionable lessons for accounting professionals across municipal, provincial, and broader public sector (BPS) entities, as well as private sector advisors:
Elevating Internal Controls Over Financial Reporting (ICFR)
The Receiver General relies on strict internal control certifications submitted by Deputy Heads and Chief Financial Officers across dozens of departments. Private and public sector organizations facing complex consolidation requirements should mimic this decentralized accountability model by implementing robust internal control sign-offs across subsidiary business units.
Navigating Discount Rate Volatility
Corporate finance leaders and public sector comptrollers must manage the impact of shifting bond yields on environmental remediation and pension provisions. The federal government’s transparent disclosures regarding sensitivity analyses (e.g., measuring the impact of a 100-basis-point swing in discount rates on pension liabilities) serve as an exemplary model for private and mid-market organizations preparing for year-end audits.
Audit Trail Architecture for Non-Financial Assets
A frequent area of Auditor General scrutiny involves physical verification and impairment testing of tangible capital assets. The federal government’s progress demonstrates the imperative of integrating Enterprise Resource Planning (ERP) systems with fixed asset registers to ensure that depreciation rates and remediation triggers are updated in real time rather than during year-end reconciliation sprints.
The Road Ahead: Future Standards and Sustainability Disclosures
As the Public Sector Accounting Board (PSAB) continues its international convergence trajectory and expands non-financial reporting guidelines, future editions of the Public Accounts will face emerging demands. Canadian CPAs should monitor two transformative areas already on the horizon:
- PSAB’s International Strategy (IPSAS Alignment): Ongoing reviews into harmonizing Canadian standards with International Public Sector Accounting Standards (IPSAS) will impact revenue recognition rules for transfer payments and non-exchange transactions.
- Public Sector Climate and Sustainability Disclosures: In response to the launch of Canadian Sustainability Disclosure Standards (CSDS 1 and CSDS 2) by the Canadian Sustainability Standards Board (CSSB), demands are mounting for governments to publish audited ESG metrics, measuring carbon emission reduction expenditures and physical asset vulnerability directly alongside traditional sovereign financial balance sheets.
The 2025–26 Public Accounts of Canada establish that despite navigating turbulent global macroeconomic currents and complex cross-jurisdictional obligations, federal accounting controls remain exceptionally resilient. For Canadian accountants, controllers, and auditors, the federal ledger stands not just as a historical record of fiscal governance, but as an indispensable playbook for modern financial accountability.